
 Add as a preferred source on Google
Bitcoin preferred share market hinges on issue size, with room for Strive and Strategy
Strive CEO Matt Cole said larger preferred share offerings attract institutional demand, while issuer exposure limits leave room for both Strive and Strategy.

Issue size and investor composition are key factors in the growth of Bitcoin preferred shares. Institutional limits on exposure to individual issuers leave room for several companies to offer similar products.
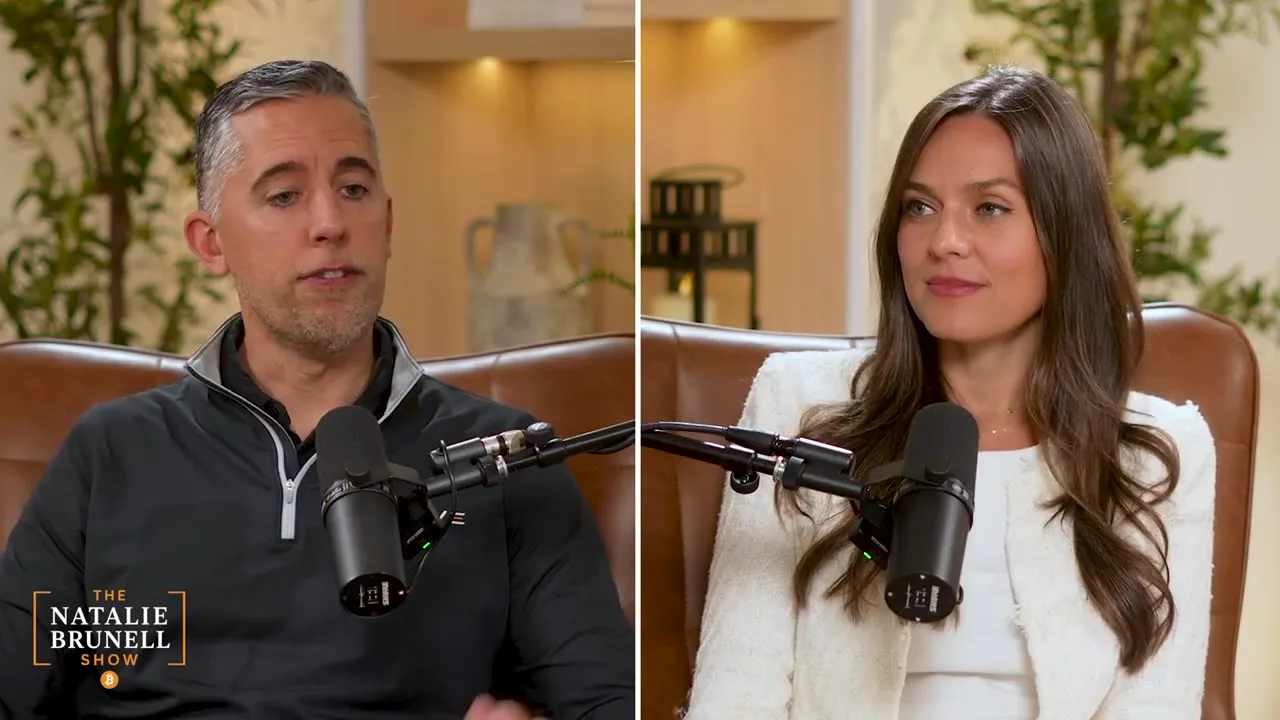
In a November 17 interview with Natalie Brunell, Strive CEO Matt Cole described how the company built its preferred share business around its Bitcoin holdings. Larger offerings, he said, can attract institutions that would otherwise find an investment too small to consider.
Strive increased its initial SATA preferred share offering from $125 million to $200 million. Cole said some institutions declined to participate at the original size because limits of 5% or 10% of an issue would leave them with positions too small to matter to their portfolios. Increasing the offering size attracted greater oversubscription, he said.
Institutional diversification requirements also support multiple issuers, according to Cole. Investors face limits on their exposure to both Strategy and Strive, creating demand for securities from different companies even when the products are identical. He said achieving sufficient scale was a greater concern at launch than the possibility of Strategy dominating the market.
Cole said Strive designed its initial capital structure to support a preferred share launch. Going public through a reverse merger gave it a shelf registration and immediate access to an at-the-market equity offering program. The company rejected debt and convertible notes, starting with Bitcoin holdings and no leverage so it could issue preferred shares quickly when demand emerged.
The bear market made product launches harder for competitors but gave Strive an opportunity to demonstrate the business could endure a downturn, Cole said. Maintaining liquidity and dividend reserves while SATA continued trading helped strengthen investor confidence. Feedback from investors in the first product also directly informed the development of its subsequent preferred share offering, SATS.
Cole attributed the decline in preferred share prices to investor borrowing. He said Strategy’s larger STRC product had attracted more leveraged positions through traditional brokerages, with forced liquidations and higher margin requirements at some firms adding to selling pressure. SATA’s less leveraged investor base did not suffer the same gap in demand, he said, describing the difference as a result of market structure rather than actions by either issuer.
Strive’s higher preferred share yields do not make its products inherently better, Cole said. Its common shares are more sensitive to Bitcoin price changes and more volatile, while its preferred shares offer higher yields. He argued that institutional demand leaves room for multiple issuers alongside Strategy, whose large Bitcoin holdings he identified as a long-term advantage.
Riza Dagoc
Riza Dagoc reports on regulation, investing and the digital-asset business for TokenPost. Send corrections or tips to info@tokenpost.com.